 UAE
 KSA
Industry Solutions
How UAE Equipment Rental Companies Can Simplify VAT Invoicing and Billing Workflows
October 30, 2026
Introducing QuickDice ERP - The Premier Accounting Solution for UAE Businesses with Exceptional Results!
How to Maintain Audit-Ready Financial Records for Your UAE Business
Table of Contents
Maintaining reliable financial records is essential for every UAE business that wants to operate with confidence, transparency, and proper financial control. Audit-Ready Financial Records make businesses aware of their financial status, enable proper reporting as well as reacting effectively when their financial records are audited. Businesses ought to plan out invoices, receipts, bank statements, approvals and transaction details all year round, rather than waiting till the audit has been announced. Effective management of records alleviates pressure and avoids unnecessary errors and important financial information is readily available when required.
The structured approach will also facilitate compliance and informed business decisions. Using FTA Approved Accounting Software can help centralize financial information, organize supporting documents, track transactions and simplify reporting processes. Companies like Quickdice ae would be in a position to implement regular accounting methods as opposed to making last minute amendments. Through structured documentation and periodic review financial teams will be able to detect anomalies earlier and have a clearer understanding of business operations and establish a more efficient base of financial management.
Audit-ready records are the full, accurate, up-to-date and well-supported financial records that do not require a lot of reconstructions. They contain details of transaction, invoices, receipts, contracts, bank statements, payroll and tax records and other pertinent documents. Every transaction must be appropriately documented, coded and must be attached to evidence.
Effective record system will also give good audit trails, frequent reconciliations, standard reporting of financial reports and easy access to documents. The accounting period should have the information properly organized, and any changes should be tracked to the authorised people. By keeping good records, reviewers can tell how the figures were obtained and the flow of financial transactions within the business.
Keeping clean records will provide UAE businesses with increased financial transparency and compliance control can be easier to manage. With easy access to transactions and other documentation, the finance teams are able to prepare themselves to the audit in a shorter period and minimize chances of overlooking any significant information. Good records are also useful in helping to trace the business transactions and a check on financial activity.
Proper records contribute to improved decision-making since the business owners will be able to base their decisions on up-to-date financial data. Periodic reviewed records enhance the accuracy of reporting, assist in detection of discrepancies and minimize the administrative delays. They also enable the management to have a better understanding of the income, expenses, liabilities, cash flow and financial performance of the business in general.
Keep accurate, timely records of all sales, purchases, expenses, payments, receipts and adjustments. Use uniform accounts classification and dates of transactions. Financial Records that are prepared to be audited should be prepared with actual business activity and all amounts and descriptions of the business and supporting evidence to be entered properly to reduce the number of errors and extra corrections.
Retain invoices, receipts, contracts, bank statements, payment confirmations, purchase orders and approval records along with pertinent transactions. Digital folders are supposed to be named in a similar manner. Regularly scheduled Audit-Ready Financial Records facilitate the ease of supporting evidence to be found and saves time in search during reviews or audits.
Periodically compare bank statements with accounting records to detect missing transactions or duplication or incorrect amounts or unexpected differences. Reconciliation is timely and ensures that there is accuracy in balances and enhances financial visibility. The differences would be researched, recorded and rectified immediately as opposed to being kept on records in subsequent times.
All financial changes are to be clearly explained with a reason, date and a history of approval. The audit-Ready Financial Records must enable the reviewers to track the transactions starting with their initial entry to subsequent alterations. Keeping user records, supporting documents, the evidence of approval and explanations of adjustments make it accountable and enhance the trustworthiness of reported information.
Do not leave an end-of-year inspection of financial documents. Provide periodic reviews to find out the unusual transactions, incomplete documentation, misclassification, and reporting anomalies. Frequent reviews enable businesses to rectify issues as information is easily accessible, thus saving them the effort of having to conduct formal financial reviews.
Establish transparent processes to approve transactions, claim expenses, pay, reconciliations and financial adjustments. Delegate duties based on the job of employees and have the right levels of authorization. Well-defined controls minimize the chances of unauthorized modifications, payments twice, incorrect entries and unrecorded financial transactions on the accounting system.
Use a centralized system to keep accounting information and supporting documents accessible to authorized personnel. It is important to avoid keeping valuable records in different spreadsheets, personal computers, emails as well as physical folders. An organized system enhances consistency, enhances document management and enables financial teams to access information effectively when necessary.
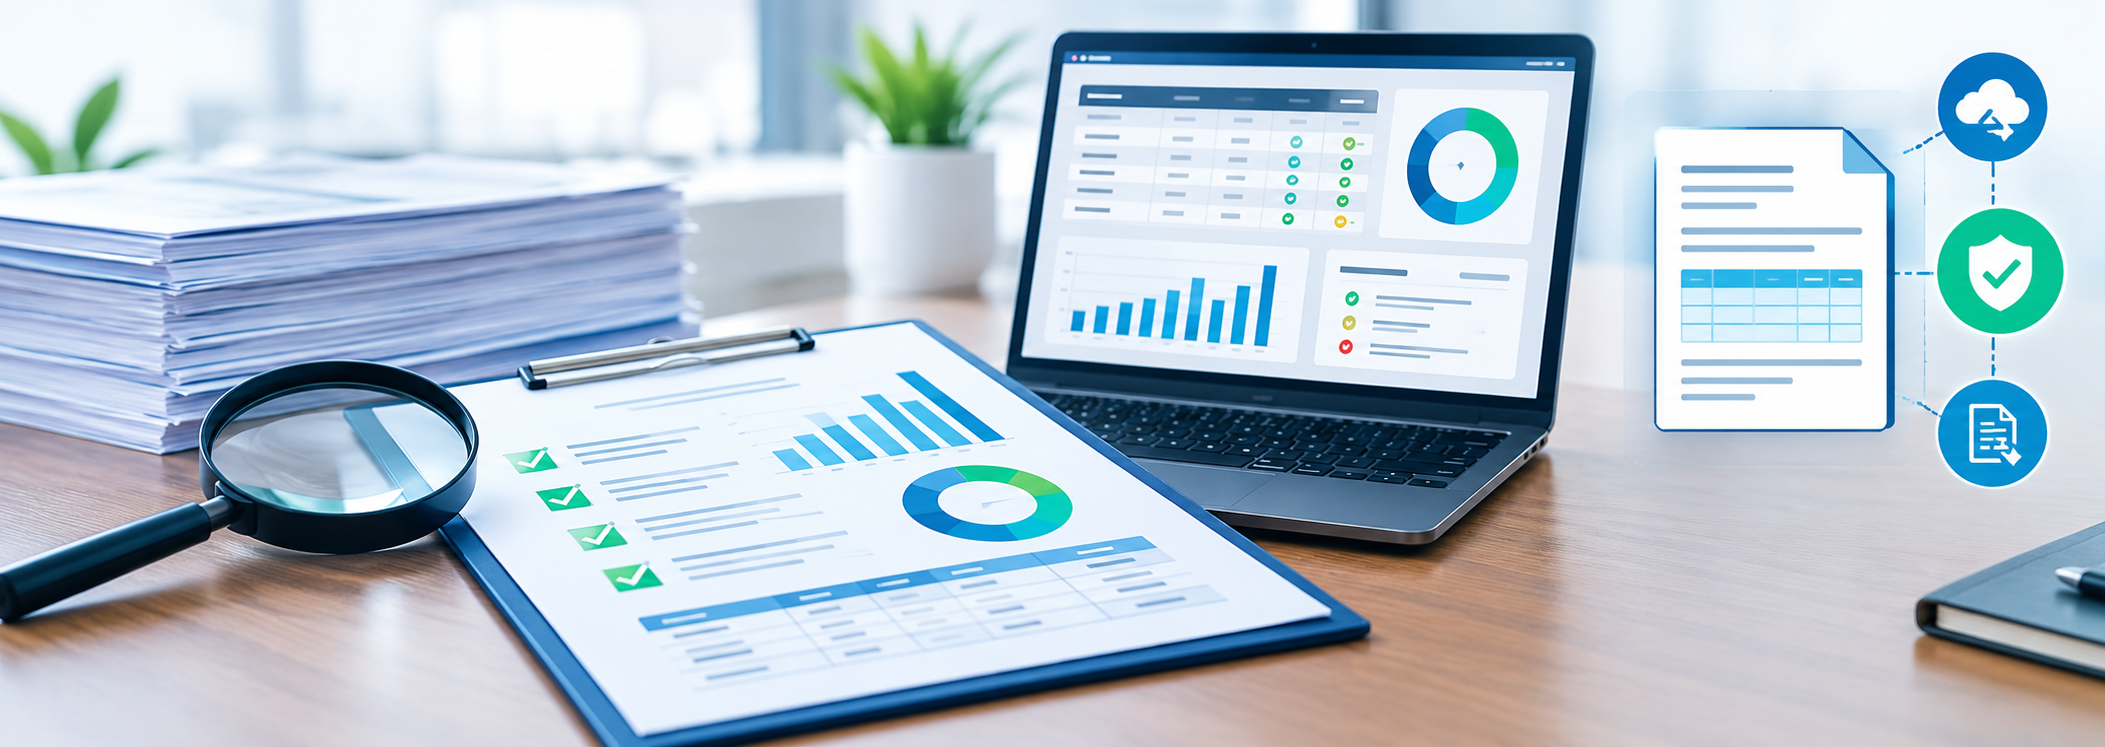
Accounting software may reduce the burden of keeping financial records by consolidating the necessary information into a single location. It is capable of assisting in automated record keeping of transactions, storing digital documents, bank reconciliation, reporting of financial transactions as well as tracking the history of transactions. Audit-trail capabilities can demonstrate changes and activity of users, documents can be more easily retrieved out of searchable records. Centralized finance data not only minimizes reliance on loosely linked spreadsheets, but it also allows businesses to have uniform information in accounting procedures.
Audit-Ready Financial Records should be a business practice and not an activity that is carried out just before an audit is approaching. Immediacy in recording transactions, maintenance of supporting documentation, account reconciliation, reviewing reports, maintenance of approval records and proper financial controls among other factors will go a long way in enhancing the reliability of business information. The practices also assist UAE businesses to take pressure off the administration and react more assuredly in cases where financial records require review.
This can be further facilitated by technology that will centralize financial information, automate routine accounting tasks, keep a history of transactions and making it easier to retrieve documents. By integrating regular accounting practices with appropriate accounting technology, a business can build a more transparent and manageable financial environment and assist in reliable reporting and enhanced long-term financial control.
They are precise, comprehensive and structured documents that are easily checked and scrutinized.
Business establishment is expected to keep invoices, receipts, contracts, bank statements, payment records, tax documents and financial reports.
Organizations ought to balance their financial statements on a regular basis usually once in a month.
The audit trail aids in monitoring the financial transactions, changes, approvals and adjustments to enhance accountability.
Yes, financial data and records can be organised, automated, assisted with reconciliation, and reporting made simple with accounting software.
It is able to centralize the financial information, organize the transaction, facilitate reporting and make the records more accessible.